
First Home in Alfreton Unaffordable? Don’t Rule Yourself Out.
Think buying your first home in Alfreton is out of reach? House prices only tell half the story. Mortgage costs, deposits and your monthly budget all matter. At Cope & Co., we look beyond the headlines to explain what the affordability figures mean today, where the challenges remain and how to turn the dream of your first home into a workable plan.
Saving for your first home can feel like chasing a moving target. House prices, rent, everyday bills. Just as you make some progress, something else needs paying for.
The local estimates put the price of a typical Alfreton first home at £177,286. A 5% deposit would therefore be around £8,864. That is a substantial sum before you have paid for legal work, a survey or moving day.
But there is a more encouraging part of the picture. The affordability figures suggest that mortgage payments take a smaller share of income than they did at several difficult points in the past.
Personally, I think that deserves a closer look. It could help buyers make a realistic plan rather than assume that home ownership is out of reach.

The asking price only tells part of the story
You have probably heard someone say, “We only paid £40,000 for our first house.” For someone looking at today’s prices, that can be a fairly frustrating conversation.
The local figures put a typical Alfreton first-time buyer home at £43,886 in 1989. However, much higher mortgage interest rates meant that a smaller loan could still put considerable pressure on the monthly budget.
The affordability estimate for that year puts mortgage payments at 42.5% of income. In 2007, the figure was 38.7%. Both are considerably above the 28.9% estimate for 2026.
That does not settle a debate about which generation had it hardest. It shows why the purchase price alone cannot tell you whether a home is affordable. What matters is the cost of borrowing alongside the money coming in and everything else that needs paying for.

The recent figures offer some encouragement
The rise in borrowing costs made 2023 particularly uncomfortable for buyers. The local affordability estimate reached 34.5% of income that year, before easing in the following years.
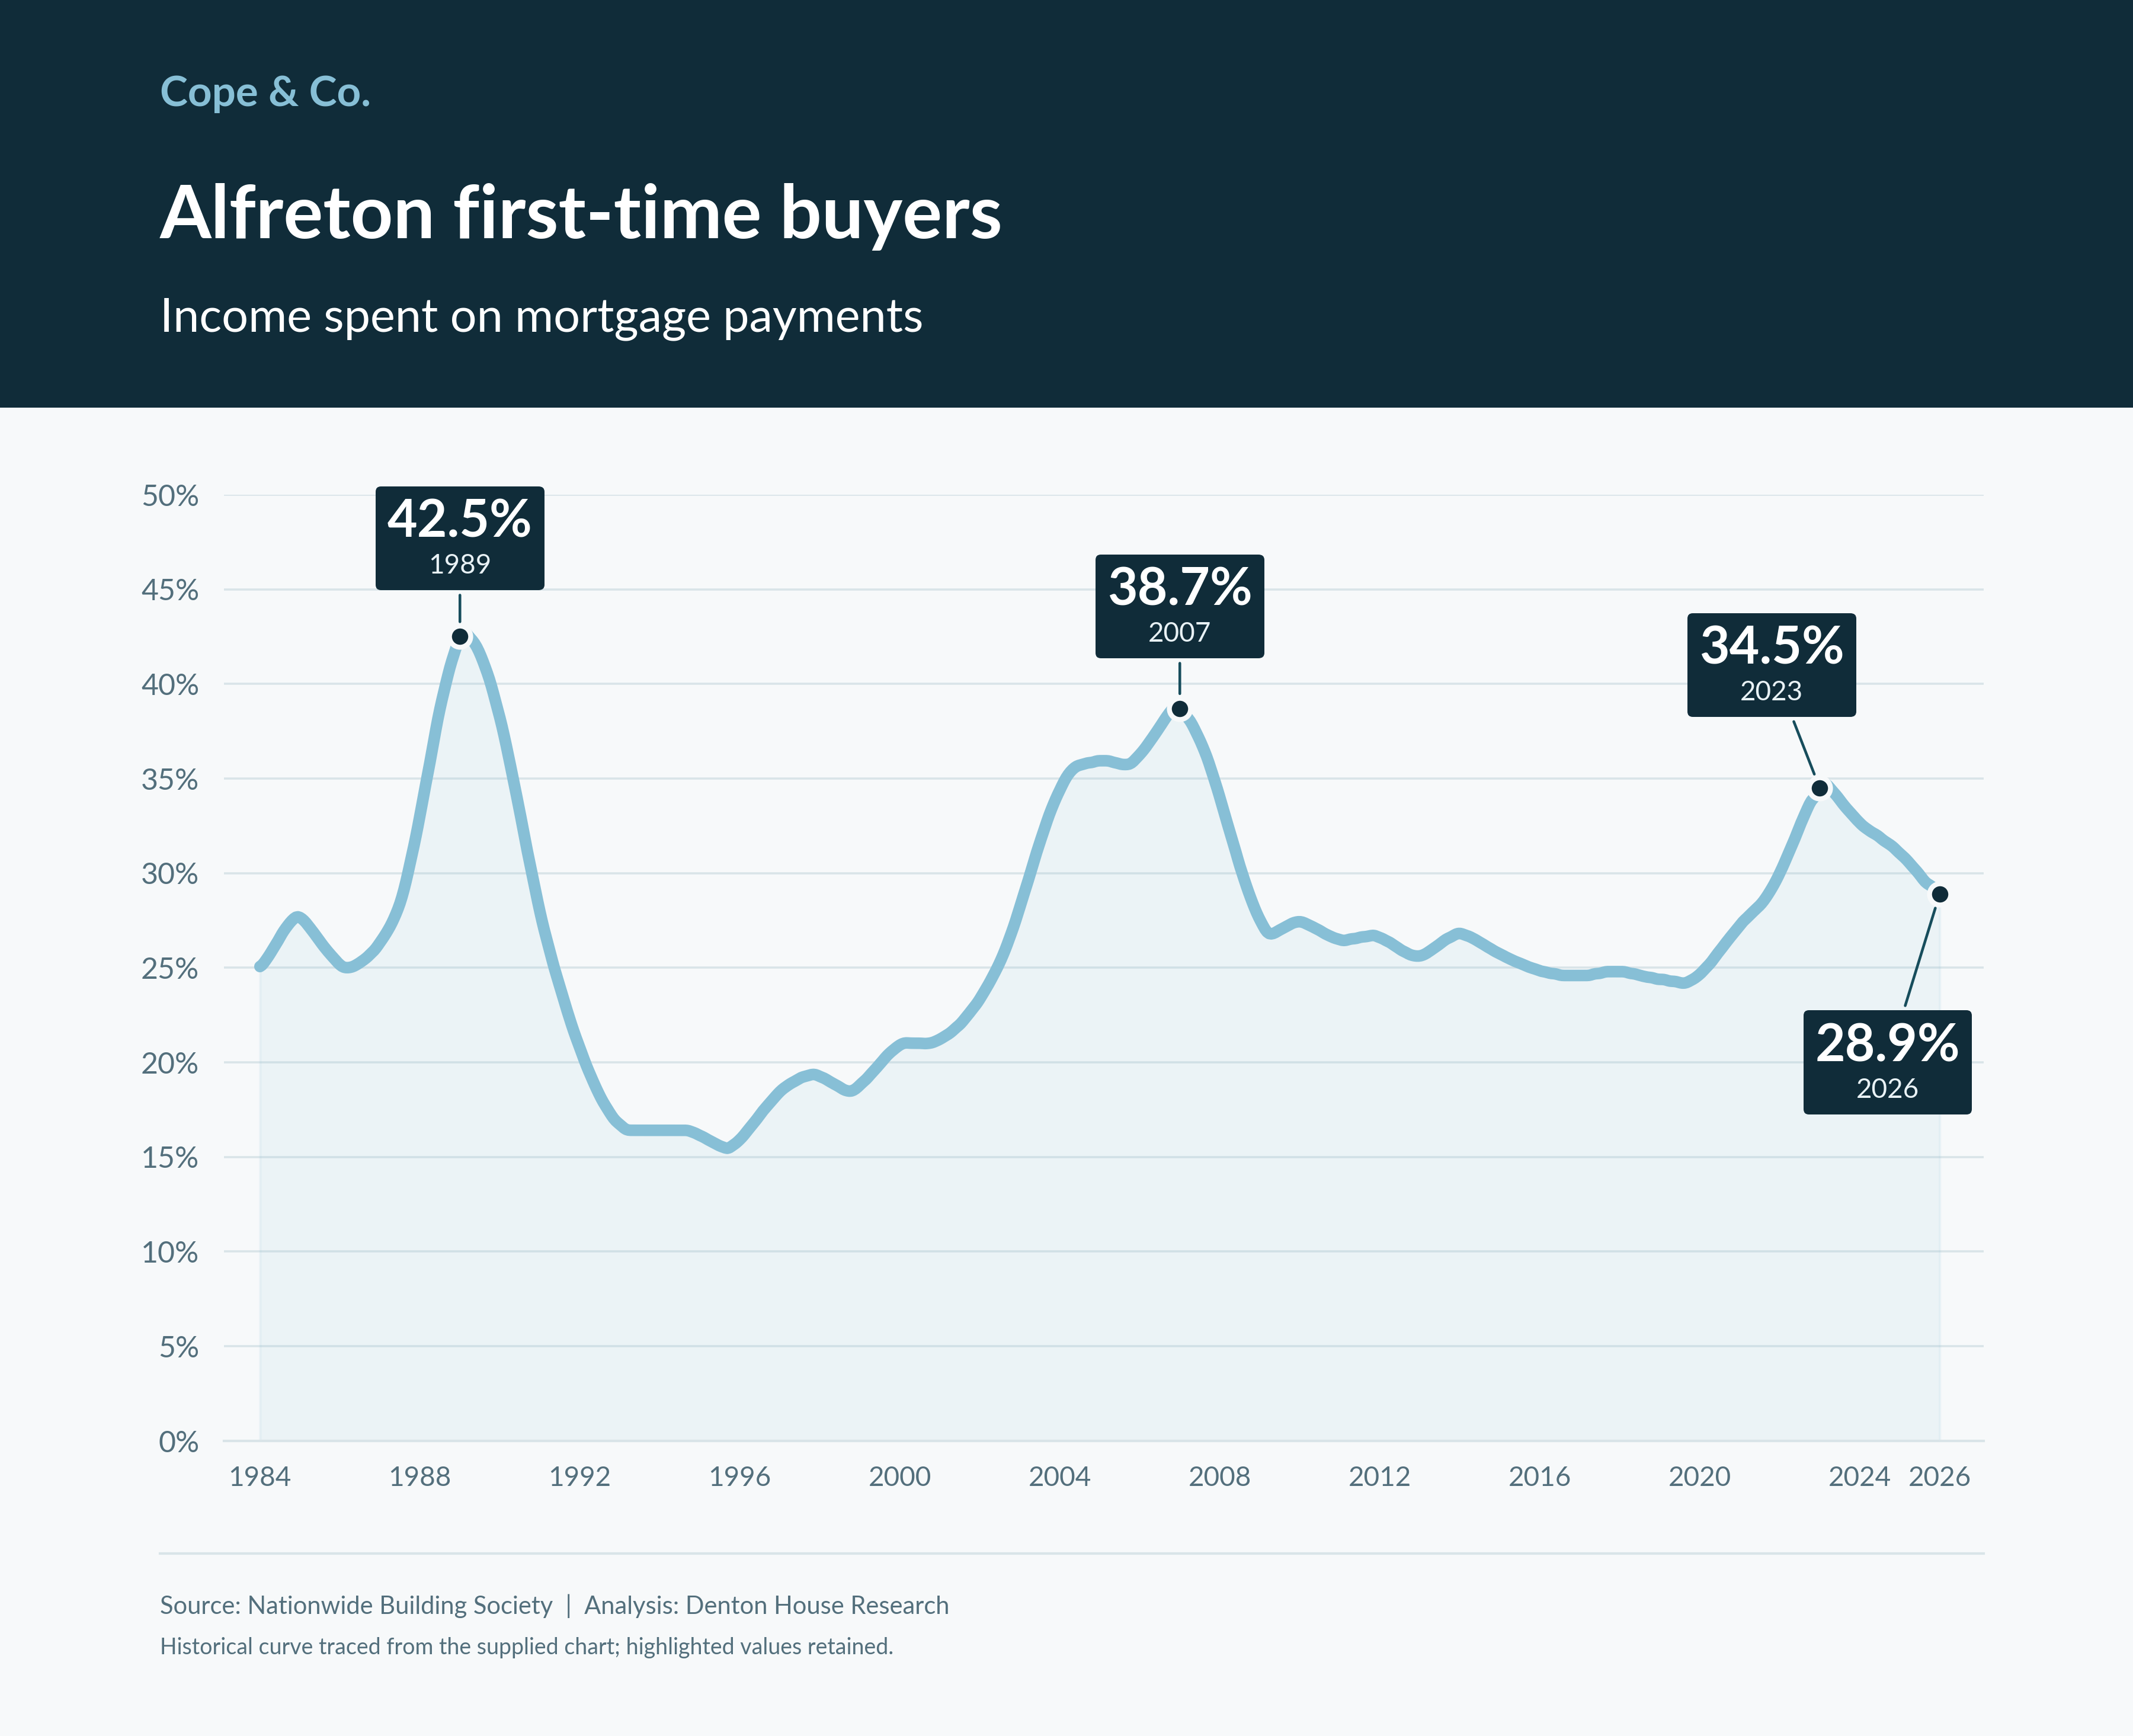
On these figures, the share of income needed for mortgage payments in 2026 is roughly 32% lower than in 1989 and 25% lower than in 2007. That is a useful perspective when the headlines make buying a first home sound impossible.
These are affordability estimates, though. The income measure, deposit size and mortgage term used in any comparison matter. They are useful for understanding a trend, but they cannot tell you what a lender will offer you or what your own repayments will be.

The deposit is still a very real hurdle
There is an obvious catch. Being able to manage a monthly mortgage payment and being able to save the deposit are two different challenges.
If rent and bills absorb most of your income, finding that £8,864 can take time, and a deposit should not leave you with an empty bank account. You will also need to allow for buying costs, any essential work and a financial cushion for unexpected expenses.
A 5% deposit is an illustration, rather than a promise that a suitable mortgage will be available. Your circumstances and the lender’s criteria will determine your options. It should not be assumed that the affordability percentages above apply to a buyer putting down 5%.
For some buyers, the sensible next step will be to keep saving. For others, a conversation with a qualified mortgage adviser may show that a purchase is closer than they thought.

Start with a monthly budget you can live with
Before you spend every evening scrolling through property listings, work out what owning a home could comfortably cost you.
Allow for the mortgage, council tax, utilities, insurance and maintenance, alongside your existing commitments. Keep some room for savings and for enjoying life. A home should fit your budget without every unexpected bill becoming a crisis.
Then ask a qualified mortgage adviser to explain your options using your actual income, deposit and commitments. Explore how the repayments could change when an initial deal ends, and how you would cope if your income fell or your costs rose.
The amount a lender is prepared to offer may be higher than the amount you feel comfortable borrowing. Set your search budget around a payment you can sustain.

Turn the figures into a plan for your first home
The figures offer encouragement, but your circumstances should decide the timing. You may be ready to buy, or you may need a little longer to build your deposit. Either way, understanding your options gives you something useful to work towards.
Once you know your budget, our Alfreton team can help you understand what it could buy locally and which properties suit your priorities. As an experienced estate agent in Alfreton, we can also explain the buying process, so you know what to expect from your first viewing through to collecting the keys.
You can register your requirements with Cope & Co. and ask about 'Earlybird Edge', which gives registered buyers access to selected homes before they reach the property portals.
If you are thinking about buying your first home in Alfreton, come and talk to our team on King Street. We will help you make sense of the local market and work out a practical next step.